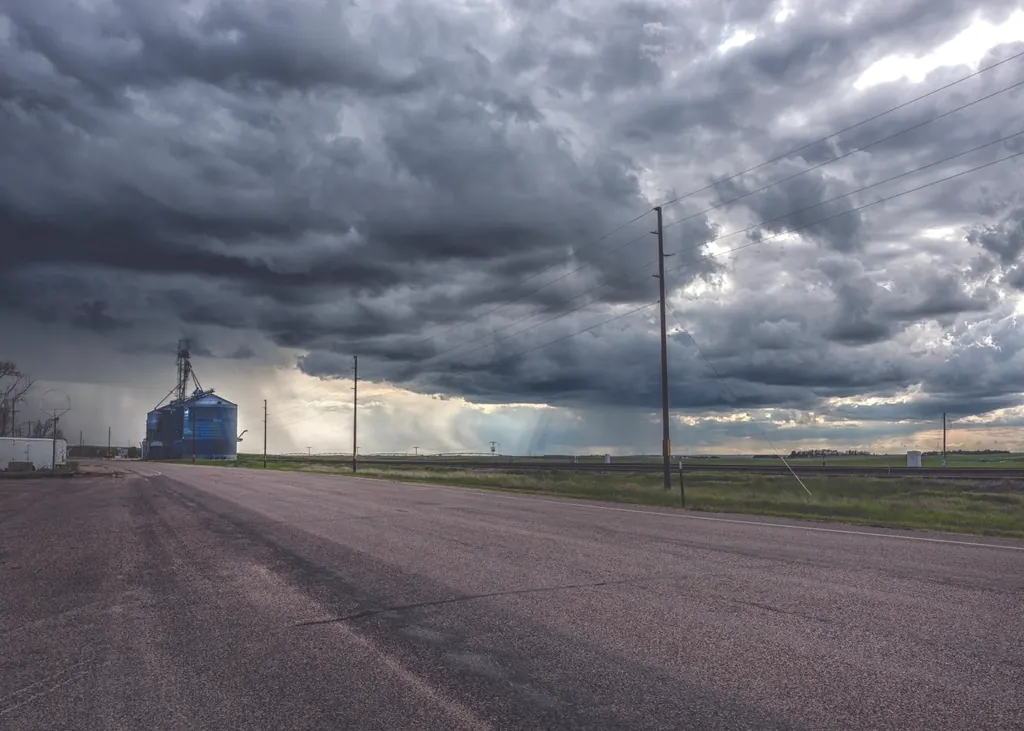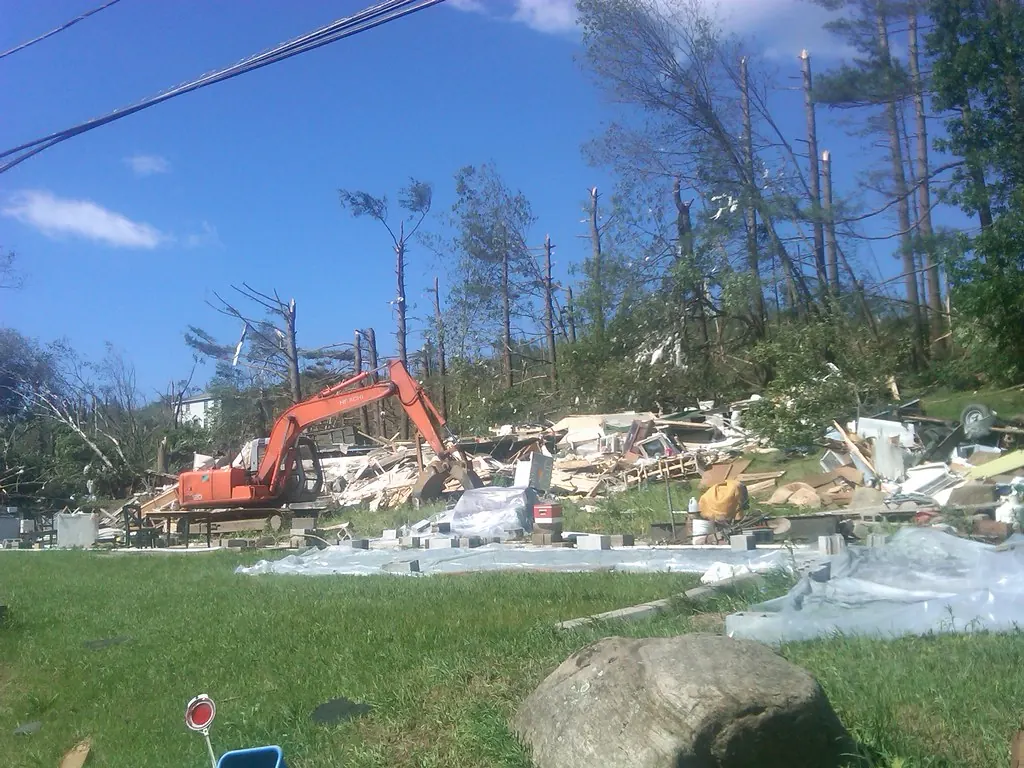
Missouri knows wind. The May 22, 2011 Joplin EF5 tornado was one of the deadliest and most destructive in modern U.S. history. A month earlier, the April 22, 2011 Good Friday tornado tore through north St. Louis County and struck Lambert airport. The May 22, 2019 Jefferson City EF3 tornado hit the capital overnight, and the December 10, 2021 outbreak brought a tornado through St. Charles County near Defiance. Add the summer derechos and straight-line wind storms, like the July 2006 storms that left much of the St. Louis area without power, and wind claims become a regular part of life here.
Partial wind losses
Most wind claims aren’t total losses. They’re missing shingles, lifted ridge caps, torn siding, broken windows, damaged fences and a tree on the garage. Disputes usually come down to scope:
- Whether a roof with scattered creased and missing shingles can be repaired or needs a slope or full replacement.
- Whether siding can be patched with matching material or needs a full elevation.
- Whether interior damage from rain getting in through wind openings is fully included.
- Whether tree removal and debris haul-off are priced correctly and within policy limits.
Total and near-total losses
Rebuild cost vs. policy limits
When a home is destroyed, the question becomes what it costs to rebuild a comparable house today. After a large event, labor and materials can spike as every contractor in the region gets booked. An estimate written from a pricing database the week after the storm may not reflect what rebuilding actually costs months later.
Ordinance or law
Rebuilding means meeting the current building code. That can add costs for things like updated electrical service, egress windows, energy code insulation or foundation requirements. Many policies cover those costs only up to an ordinance-or-law limit, often a percentage of the dwelling limit. The limit is a coverage term; the cost of complying is something appraisal can help value.
Debris removal and demolition
Clearing a site after a tornado isn’t cheap. Policies usually treat debris removal as part of the dwelling limit with some additional amount on top. Read that section carefully.
Wind vs. other causes
Carriers sometimes attribute roof or siding damage to age, installation defects or wear rather than wind. When causation is the core of the dispute, appraisal may not resolve it, because appraisers don’t decide coverage. When the carrier accepts wind damage but disputes how much, appraisal fits well. If a tornado brought heavy rain with it, keep in mind that flood and surface water are usually excluded from homeowners policies and need separate flood insurance.
For example, an illustrative total-loss claim might show a carrier rebuild figure of $260,000 while local builders quote $340,000 for a comparable home under current code. Appraisal looks at documented rebuild costs; it doesn’t raise your policy limits.
Living expenses while you rebuild
Additional living expense (ALE) or loss of use pays for temporary housing and the extra costs of being displaced. After a big tornado, rental housing gets scarce fast. ALE disputes can sometimes be part of an appraisal when the question is the amount rather than coverage. Keep every receipt.
What to do in the first weeks
- Make the property safe and prevent further damage; keep receipts for tarps and board-up.
- Photograph everything before cleanup, including debris piles and contents.
- Get a certified copy of your policy and note your dwelling, other structures, contents, ALE and ordinance-or-law limits.
- Get the carrier’s estimate in writing and compare it to local contractor bids.
Our appraisal roadmap explains what happens after a demand. For a line-by-line look at the carrier’s numbers first, see insurer estimate review.
Questions about tornado & derecho wind appraisal
Is a derecho covered the same as a tornado?
Generally both fall under windstorm coverage in most homeowners and commercial policies. Your policy may have a separate wind or hail deductible, so check the declarations page.
Can appraisal increase my policy limits?
No. Appraisal sets the amount of loss. Payment is still capped by your policy limits, including any ordinance-or-law and debris removal limits.
What if the insurer says the damage is old wear rather than wind?
That’s a causation dispute, and appraisers don’t decide coverage. Depending on the policy wording, a Missouri attorney may need to weigh in before appraisal makes sense.