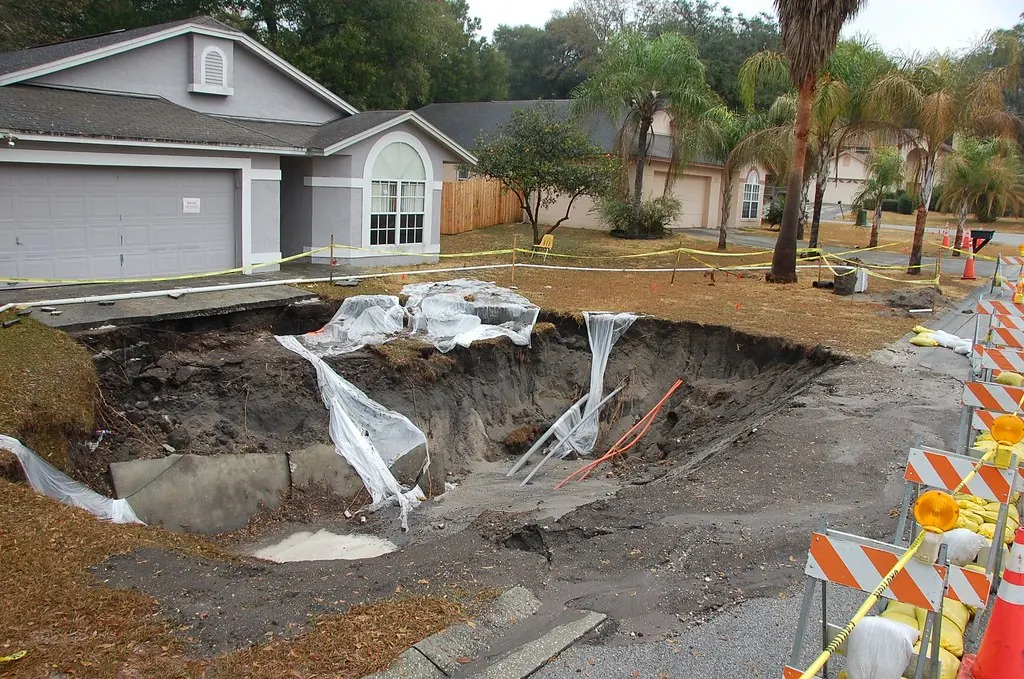
Much of Missouri sits on limestone and dolomite that slowly dissolve as groundwater moves through them. Geologists call that karst. It’s why the state is known for caves and springs, and it’s why Missouri has thousands of mapped sinkholes. The Missouri Geological Survey, part of the Missouri Department of Natural Resources, maps known sinkholes across the state. They’re most common in the Ozarks and southern Missouri, around Springfield and Greene County, and in parts of eastern Missouri, including limestone areas of the St. Louis metro.
Coverage comes first, and it’s often the hard part
This is the most important point on this page. Most standard homeowners policies exclude earth movement, and that exclusion is commonly written broadly enough to include sinkholes, settling and subsidence. Whether a sinkhole loss is covered often depends on:
- Specific collapse coverage in the policy and how it’s worded.
- Any endorsement you added for sinkhole or ground collapse.
- How the policy defines collapse and what causes it lists.
- Whether the damage is ongoing settling or a sudden event.
An appraiser doesn’t decide any of that. Appraisal values the amount of loss once coverage is accepted. If the carrier has denied the claim based on an earth movement exclusion, that’s a coverage dispute for a Missouri attorney, not an appraisal question.
When appraisal does fit a sinkhole claim
Sometimes the insurer accepts that a covered collapse or sinkhole event occurred, under a collapse provision or endorsement, and then offers a repair figure the owner can’t make work. That’s where appraisal can help.
Foundation and ground stabilization
Repairs can range from compaction grouting or underpinning to piers and slab replacement. An engineer’s report usually drives the scope. Appraisers compare competing repair methods and their costs, while staying within whatever the policy and endorsement actually cover.
Structural and finish damage
Cracked walls, racked door frames, separated brick veneer, broken plumbing and uneven floors all follow foundation movement. These finish repairs often add up to more than people expect.
Endorsement limits
Sinkhole or collapse endorsements may carry their own limits or deductibles. The award values the loss; the endorsement terms decide what’s paid.
| Question | Who decides |
|---|---|
| Is earth movement excluded? | Policy wording; attorney if disputed |
| Did a covered collapse occur? | Carrier; courts if disputed |
| What causes the damage? | Engineers, carrier, courts |
| How much does repair cost? | Appraisal panel, once covered |
Practical steps if the ground opens up
- Keep people away and call local authorities if the hole is near a structure, road or utility line.
- Report it to your insurer promptly and in writing.
- Photograph the hole, cracks and any changes over days or weeks.
- Check the Missouri Geological Survey’s sinkhole information for your area.
- Get a structural or geotechnical engineer involved early; their report will shape everything.
Not every crack or sunken patch is a sinkhole. Settling from poor compaction, drought-shrunk clay soils or leaking pipes can look similar. Cause matters for coverage, and appraisers don’t decide cause or coverage.
Earthquake is a different policy question
Southeast Missouri sits in the New Madrid seismic zone, and earthquake damage is generally excluded from standard homeowners policies. Earthquake coverage is usually a separate endorsement you have to choose and pay for, and it often comes with a percentage deductible. If you live in the Bootheel, Cape Girardeau or the St. Louis region and haven’t looked at this, it’s worth a call to your agent. Sinkhole and earthquake damage are separate perils, and one doesn’t stand in for the other.
For definitions of collapse, subsidence and related terms, see our appraisal dictionary. Unsure whether your claim is at the appraisal stage? Reach out and we’ll tell you honestly.
Questions about sinkhole & ground collapse appraisal
Does Missouri homeowners insurance cover sinkholes?
Usually not under a standard policy, because most exclude earth movement. Coverage may exist through specific collapse wording or an endorsement, so read your policy and ask your agent.
Can an appraiser decide whether my sinkhole damage is covered?
No. Appraisal only sets the amount of loss once coverage is accepted. Coverage and causation disputes belong with your insurer and, if needed, a Missouri attorney.
Where can I check whether sinkholes are mapped near my home?
The Missouri Geological Survey, part of the Missouri Department of Natural Resources, maintains sinkhole mapping for the state.
Is earthquake damage covered with sinkhole coverage?
No. Earthquake coverage is usually a separate endorsement you have to choose, and it’s distinct from any sinkhole or collapse coverage.