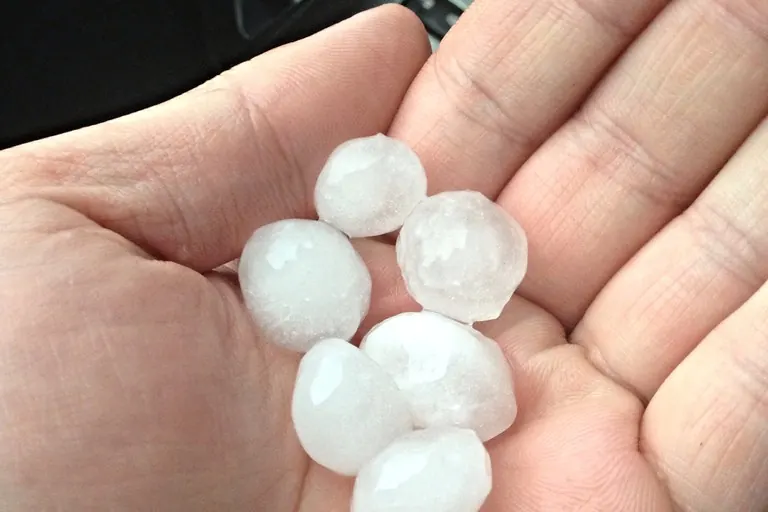
Missouri is one of the busier hail states in the country. Storms build along the I-70 and I-44 corridors every spring, and a single afternoon cell can mark thousands of roofs from Columbia to the St. Louis suburbs. The April 10, 2001 hailstorm along the I-70 corridor in the St. Louis area was one of the costliest hail events of its time, and big hail days have kept coming since. When the claim comes back as “a few shingles and a gutter,” appraisal is often how homeowners and building owners get the full roof looked at fairly.
What a hail roof dispute usually looks like
The insurer agrees hail hit the property. The disagreement is how much damage there is and what fixing it requires.
- Repair vs. replace. The adjuster counts hits on a test square and decides the slope can be patched. Your roofer says the shingles are brittle and can’t be repaired without breaking more.
- Discontinued shingles. If your shingle line is no longer made, a repair may leave a visible patch. How that’s handled depends on your policy and the facts.
- Matching. Some policies address matching directly; some limit it; some are silent. The wording controls.
- Soft metals. Dents in gutters, downspouts, vents, flashing and AC fins are evidence of hail size and direction, and they’re often damaged in their own right.
Functional vs. cosmetic damage
A growing number of policies sold in Missouri include a cosmetic damage exclusion or limitation, most often for metal roofs and siding. Under that language, dents that don’t affect the roof’s ability to shed water may not be covered. Whether a given dent is “cosmetic” or “functional” is often argued hard.
What appraisal can address
If coverage is accepted and the fight is about how many panels or squares need replacing, that’s generally an amount-of-loss question. Appraisers measure, count and price.
What appraisal can’t address
If the carrier says all of the damage is cosmetic and excluded, that’s a coverage position. An appraiser doesn’t decide coverage. A Missouri attorney can advise on that.
How we document a hail loss
- Confirm the storm date with weather data and match it to your notice date.
- Inspect every slope, marking and photographing hits on shingles, ridge caps and vents.
- Check soft metals, window wraps, siding, screens and outdoor units on all sides.
- Identify the shingle manufacturer and line, and check whether it’s still available.
- Write a full estimate including tear-off, underlayment, drip edge, ice-and-water shield where code calls for it, and code-required items.
| Component | Common carrier position | What we check |
|---|---|---|
| Shingles | Spot repair | Hit count, brittleness, availability |
| Metal roof | Cosmetic only | Seams, fasteners, policy wording |
| Gutters | Not damaged | Dent pattern, sizing, matching |
| Siding | Replace one wall | Profile availability, color match |
Timing matters with hail
Hail damage isn’t always visible from the ground, and many people don’t learn about it until a roofer knocks on the door weeks later. Most policies require prompt notice, and some have shorter windows for wind and hail claims. Report it, get it inspected, and keep records of the storm date. Our toolkit has a storm-date checklist.
Be careful with door-knockers after a hail storm. A legitimate roofer won’t pressure you to sign on the spot. Appraisal is a separate process from choosing a contractor, and we don’t sell roofs.
After the award
The appraisal award sets the amount of loss. Depreciation holdback and deductibles still apply according to your policy, and many carriers release recoverable depreciation once you show the work is done. If you’re also facing interior water stains from a damaged roof, see water damage appraisal for how those claims are handled.
Questions about hail & roof damage appraisal
Will the appraisal panel order a full roof replacement?
The panel sets the dollar amount of loss, not a construction order. If the evidence shows the roof can’t be properly repaired, the award can reflect a replacement cost, but nothing is guaranteed.
My metal roof has dents but doesn’t leak. Is that covered?
It depends on your policy. Some Missouri policies exclude or limit cosmetic damage to metal; others don’t. Coverage is a question for the policy wording and, if disputed, a Missouri attorney.
How long after a hail storm can I file a claim?
Policies vary, and some set specific windows for wind and hail claims. Read your policy and report the damage as soon as you know about it.
Do dented gutters prove hail damage to my roof?
Not by themselves, but they’re useful evidence of hail size and direction. Appraisers look at soft metals alongside the roof covering itself.